Card Payment Surcharges Banned in Australia from 2026

Are you happy with the RBA's proposed changes to surcharging and interchange fees?


  • Total voters
    217
I never carry cash domestically except for my $15 haircuts where they don’t accept anything else.

I have noticed some people paying cash when they could or do have a credit card. Seems they use cash as a method of budget control. They draw out a set amount each week or fortnight. Every time they are about to make a spir of the moment purchase they look in their wallet and make a decision “this is what is left for x days, can I afford it”.

With a credit card the balance is opaque and they tend to overspend and sometimes get into trouble with their budgeting.
 
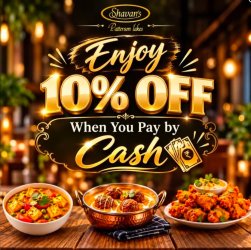
So they'll give you a 10% discount so they can avoid a <2% card fee?

Are they doing that out of spite, or trying to invite a GST compliance audit?

Seems like they can quite easily afford to absorb the card fees into their prices if they can offer 10% off!

Unless they increased their prices by 10% and this is just another ColesWorth style fake discount.
 
So they'll give you a 10% discount so they can avoid a <2% card fee?
...
Seems like they can quite easily afford to absorb the card fees into their prices if they can offer 10% off!

Unless they increased their prices by 10% and this is just another ColesWorth style fake discount.
I know the place well. Their prices have not increased by 10%.
Are they doing that out of spite, or trying to invite a GST compliance audit?
I would suspect they would be fully prepared for any GST compliance audit ...
 
Last edited:
Credit card surcharges is component pricing. No doubt at all.
Credit card surcharges are optional additional pricing more than component pricing.
Do you charge a customer for your rent costs? Electricity costs? Payroll?
No, because I can't get my service without the rent, electricity and payroll being involved, I could have gotten my service without the business incurring a credit card fee.
 
30 years ago, perhaps. Not now though. Anyone in, or starting a, business knows that they need to deal with credit card payments. There is no excuse for surcharging.
Your argument is just inane. I am still able to hand over cash to pay for a transaction. I am able to make a bank deposit. Those options have not disappeared.

If I go to the barber to get a haircut I cannot get the haircut without the barber incurring payroll expenses or electricity costs, or rent costs. Regardless of how I pay, he will incur those costs. If I pay him with cash he incurs zero credit card processing costs. If you pay via credit card, he does incur those costs. You want me to pay more in cash to subsidise your desire to pay via credit card. I don't think that socialisation should be forced.
 
But he does incur cost to process the cash. The cash doesn't magically appear in his bank account. It has to be counted, bagged, and taken to the bank, during banking hours, which takes time and time is a cost.
Which i’m guessing costs more in time and insurance premiums and everything else than the .3% surcharge?
 
But he does incur cost to process the cash. The cash doesn't magically appear in his bank account. It has to be counted, bagged, and taken to the bank, during banking hours, which takes time and time is a cost.
And if he didn't want to incur that he was free to not accept cash as long as he provided a fee free payment option. What you don't like is that when businesses were free to make their own choices they resoundingly chose to act against what you like. They chose that cash was the fee free option, not card.

That was their free choice, now they don't have that freedom.
 
At a cafe in Manly, the staff said you "have" to use the NFC tag on the table to pay after the meal and it charged a platform fee.
 
And if he didn't want to incur that he was free to not accept cash as long as he provided a fee free payment option. What you don't like is that when businesses were free to make their own choices they resoundingly chose to act against what you like. They chose that cash was the fee free option, not card.

That was their free choice, now they don't have that freedom.
Nothing of the sort. They were either too stupid, or refused, to recognise that there is a cost associated with accepting cash. Since this is true, and they accounted for it in their business model, and since the cost of card acceptance is certainly no higher, there was never a need to surcharge.
 
Nothing of the sort. They were either too stupid, or refused, to recognise that there is a cost associated with accepting cash. Since this is true, and they accounted for it in their business model, and since the cost of card acceptance is certainly no higher, there was never a need to surcharge.
Ahhhh okay, you're simply more intelligent than every successful business owner that disagrees with you. It cannot be that they think differently to you, it's that they're mentally inferior to you.

Hubris.
 
Nothing of the sort. They were either too stupid, or refused, to recognise that there is a cost associated with accepting cash. Since this is true, and they accounted for it in their business model, and since the cost of card acceptance is certainly no higher, there was never a need to surcharge.
Assuming of course that they actually record and declare the cash. Which I suspect may not happen in some cases.

Having to count cash, go to the bank, have a float, keep money in the store overnight - or take it home - and everything else can’t be cheaper than accepting a card?
 
So they'll give you a 10% discount so they can avoid a <2% card fee?

Are they doing that out of spite, or trying to invite a GST compliance audit?

Seems like they can quite easily afford to absorb the card fees into their prices if they can offer 10% off!

Unless they increased their prices by 10% and this is just another ColesWorth style fake discount.
Consider it as a promotion I'd suggest. So a marketing cost. Might make the difference between going there or elsewhere and @serfty has just spread that message. 😉
 
I'm not in small business so don't have first hand experience. However, I find a big disconnect between statements like they can't operate and will go bankrupt without a 2% cc surcharge but then belong to programs where they give a 30-40% discount in promotions every day of the week (such as eat club) or 10% loyalty cards for coffees etc
 
I'm not in small business so don't have first hand experience. However, I find a big disconnect between statements like they can't operate and will go bankrupt without a 2% cc surcharge but then belong to programs where they give a 30-40% discount in promotions every day of the week (such as eat club) or 10% loyalty cards for coffees etc
With EatClub, I've seen examples of them using it as a one-off to bring in people, but by the next week realise it's not worth it (ie no more offers).

Also saw an example, where they offered EatClub and discount for cash. EatClub discounts were disappearing within minutes after midnight. I guess the rising rents got to them as they closed a few months ago (after being years in business) and new tenants are incoming (a few more weeks for incoming tenant renovations).

Some loyalty discounts, they just hope you won't make the threshold. But honestly coffees are quite cheap to make (one extra coffee even say out of 20 won't break the bank - its the fixed cost that kill you!).

Of course every business will be different.

In my mind I felt many business put in the card surcharge once they saw competitors do so and not lose business, so an extra source of income. Same with the Sunday/public holiday surcharge. YMMV
 
Last edited:
In my mind I felt many business put in the card surcharge once they saw competitors do so and not lose business, so an extra source of income. Same with the Sunday/public holiday surcharge. YMMV
How would adding surcharges not lose business? Surely, if they had not added them, that would be a point of difference compared to their competitors?
 

Become an AFF member!

Join Australian Frequent Flyer (AFF) for free and unlock insider tips, exclusive deals, and global meetups with 65,000+ frequent flyers.

AFF members can also access our Frequent Flyer Training courses, and upgrade to Fast-track your way to expert traveller status and unlock even more exclusive discounts!

AFF forum abbreviations

Wondering about Y, J or any of the other abbreviations used on our forum?

Check out our guide to common AFF acronyms & abbreviations.

Recent Posts

Back
Top